
UAE lending moves beyond credit scores to assess borrowers, industry leaders say
Lending in the UAE is increasingly moving beyond traditional credit scores, with fintechs and banks turning to alternative data to assess customers who may have little or no formal credit history, industry leaders said at the Banking Innovation & Technology Summit (BIT) Summit in Dubai on Tuesday.
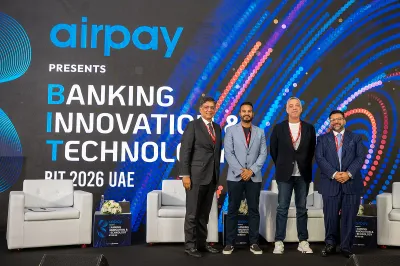
Lending in the UAE is increasingly moving beyond traditional credit scores, with fintechs and banks turning to alternative data to assess customers who may have little or no formal credit history, industry leaders said at the Banking Innovation & Technology Summit (BIT) Summit in Dubai on Tuesday.
The shift is enabling lenders to make faster and more forward-looking decisions by using data from transactions, remittances and payroll systems to understand a customer's financial behaviour, willingness and ability to repay.
For a large segment of customers, particularly those without established credit histories, such data could open access to financial services that may otherwise remain out of reach.
Stay up to date with the latest news. Follow KT on WhatsApp Channels.
But as financial institutions gain access to increasingly granular customer data, the industry faces a parallel challenge: how far personalisation should go.
Speakers at a separate fireside chat said transparency and explicit consent will be critical to ensuring data-driven financial services remain useful rather than intrusive.
UAE fintechs look beyond credit scores
Omair Ansari, CEO & Cofounder, ABHI, said lending has become a key focus for fintechs because of the margins it offers, while alternative data is opening new ways to underwrite customers.
“Every fintech dreams of becoming a bank, and all roads lead to lending when it comes to fintech because that's where the margin is, as you kind of establish that there is really no margin anywhere else. Now, the back of that is focusing on how you can underwrite to be able to provide that lending.”
Ansari said ABHI is using remittance data across markets, including the UAE, to support lending decisions, while also using Wage Protection System (WPS) data in the UAE.
“It's alternative data that you're able to use now to be able to provide lending services. We work with a lot of the remittance providers (to get us access to data) that help us in underwriting decisions."
"Majority, 99.9% of our customers, for example, have no credit score, so how do you pull data to be able to underwrite and provide them with one a basic level of service, which is what is our core product?"
Walid Hassouna, Founder & Group CEO, Valu, said the limitation of traditional credit scoring was that it largely relied on past borrowing behaviour. Reflecting on the company's experience in Egypt in 2017, he said credit bureau information mainly helped lenders make decisions based on what customers had done before.
“We would use credit scoring. The credit bureau was essentially lending to customers who had borrowed before through official lines. So, in reality, we were not adding anything. We were just looking backwards, looking at this information and making a decision.”
Hassouna said the use of multiple layers of data has since allowed lenders to make more forward-looking decisions, with changes in the data improving risk assessment and customer acquisition.
“So, what we have done (now) is use multiple marketable layers of data, and the good thing is that every time a small change has been made, our probability of default goes down and our capital-acquiring customers go up. And now we look forward, rather than backward.”
Amit Malhotra, Global Head of Retail Banking, Abu Dhabi Islamic Bank (ADIB), said the future of lending will increasingly be defined by real-time and predictive finance embedded in customers' everyday lives.
“I think the future of lending and financing, as we know it today, can be described in a few words: real-time, predictive, absolutely data-driven, customer-focused or hyper-personalised, as we call it, and, most importantly, linked to the moment.”
Rather than customers approaching banks only when they need financing, Malhotra said financial products are increasingly becoming embedded within the wider customer journey.
“Today, the consumption of finance is actually happening based on how consumers consume the end product. So, more and more, finance has been embedded in the ecosystem and in the customer lifecycle.”
Speakers (Centre) Basel Nezam, Vice President and Head of Products for Value Added Services, Network International, and (Right) Deepak Sarup, Group EVP & CBO, Thriwe,
How to deliver personalisation in a way that doesn’t seem intrusive?
The growing use of customer data, however, brings a different question into focus: where should financial institutions draw the line?
Basel Nezam, Vice President and Head of Products for Value Added Services, Network International, said obtaining customer consent can itself be difficult, particularly when businesses are trying to make services more personalised.
“Sometimes it’s easier said than done, because engaging with the customer to provide that consent can be challenging in itself. So, how do you deliver personalisation in a way that doesn’t seem intrusive? I think there are certain red lines you shouldn’t cross.”
He said sensitive information, including medical transactions, could raise ethical concerns when used for personalisation.
“For example, accessing people’s medical transactions to give them advice… or for other (confidential) purposes raises ethical questions. There are certain boundaries that you shouldn’t cross. Consent is where you start.”
Deepak Sarup, Group EVP & CBO, Thriwe, said transparency must accompany consent if banks and brands are to build lasting customer trust.
“From an ethical and moral standpoint, I think customer consent is key. As far as brands and banks can go, they need to be very transparent about how they are mining data and to what extent they want to use it.”
Sarup said explicit consent at every stage could make data use part of a broader relationship of trust, rather than simply a compliance requirement.
“If that is made as explicit as possible to the end consumer, and there is explicit consent at every stage, I guess it’s not just about ticking a box anymore. It’s actually about playing the part of a trusted partner.”
He cautioned that personalisation that is not transparent to customers can quickly become uncomfortable.
“Anything that is done in a slightly covert manner, without being very evident to the customer, I guess, also borders on becoming a little creepy.”
Dubai named world number one for fintech, moves up in global rankings
Valu profit jumps 43% as Egypt fintech broadens lending footprint